Your situation
- You own an undeveloped urban plot and receive a tax notice.
- Part of your plot is built on, or reserved for a road or a public facility by the zoning plan (plan d'aménagement).
- You wish to declare, or contest, the area taken into account.
The text in force
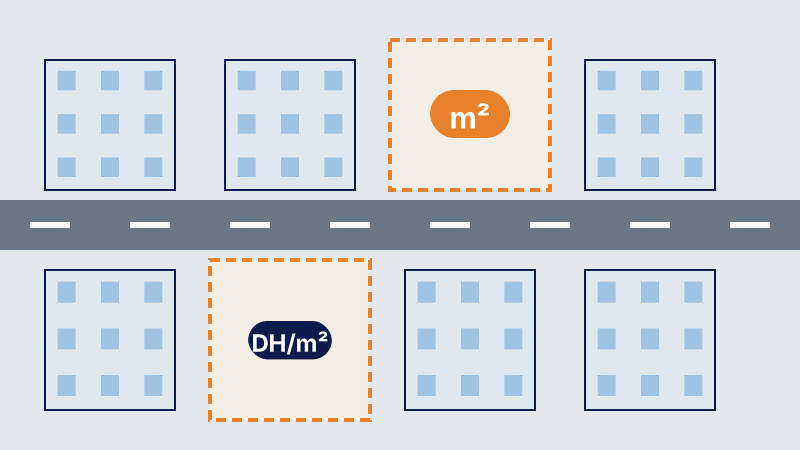
The TNB (tax on undeveloped urban land) is governed by Law 47-06 on local authority taxation, amended by Law 07-20 and then by Law 14-25, promulgated by dahir 1-25-50 of 6 June 2025 (Official Bulletin (B.O.) No. 7412 of 12 June 2025; French edition No. 7418 of 3 July 2025). It came into force on its publication. The tax is assessed on the area of the land, in square metres.
The new rates (article 45)
| Level of infrastructure of the zone | Rate |
|---|---|
| Fully serviced zone: all or most services (health, education, roads, electricity, water, sanitation, street lighting, urban transport, waste collection) | 15 to 30 MAD/m² |
| Intermediate zone: at least roads, electricity and water | 5 to 15 MAD/m² |
| Poorly serviced zone | 0.5 to 2 MAD/m² |
- the zones are delimited by decision of the president of the municipal council, enforceable once approved by the governor;
- each municipality sets its rate within these ranges;
- a tax below 200 MAD is neither issued nor paid;
- the tax is collected by the municipal tax collector.
The taxable area
The registered area entered on the land title does not always correspond to the taxable area: part of the land may be built on, occupied by light structures, or reserved for a road or a public facility by the zoning plan. These distinctions are measured on the ground and on the planning document.
The surveyor's certificate
- Base documents: cadastral plan and area computation, planning information note (note de renseignements) or zoning plan in force, property certificate.
- Field survey of the boundaries, buildings and occupations.
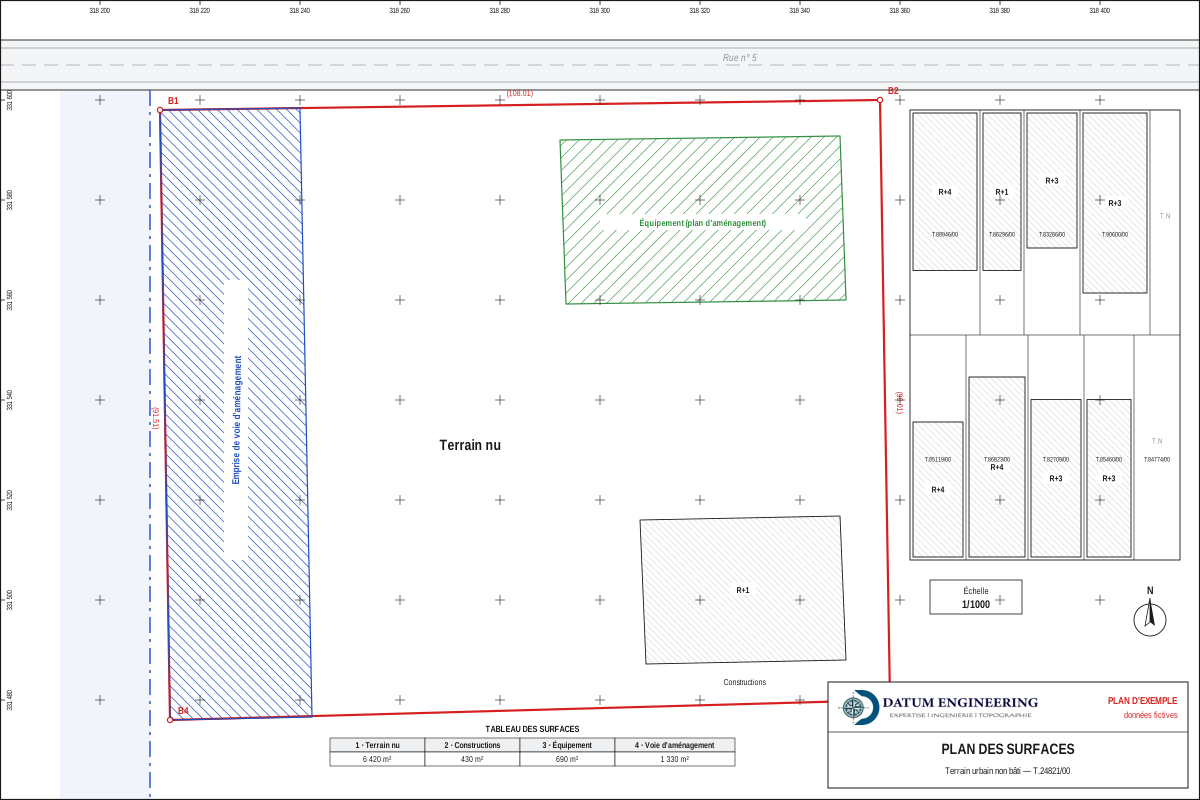
- Plotting of the zoning plan: planned roads, facilities and zones.
- Computation of the areas by category and summary table.
- Area plan and certificate assessing the taxable and non-taxable areas, signed by the sworn surveying engineer (IGT), to be attached to the declaration or the claim.
Frequently asked questions
Does the rate still depend on the urban category?
Since Law 14-25, it depends on the level of infrastructure of the zone, delimited by decision of the president of the municipal council approved by the governor.
Is the tax levied on the whole area of the title?
It is assessed on the area of the land; the surveyor's certificate distinguishes the taxable and non-taxable areas under the law and the zoning plan.
Who collects the tax?
The municipal tax collector, the public accountant responsible for collecting municipal taxes.
Other useful guides
 Property valuation: how the value of an apartment or a plot of land is estimatedInheritance, sale, partition or loan: how the market value of an apartment or a plot of land is estimated in Morocco, methods and documents.
 Alignment plan: knowing where to build in relation to the public roadAlignment plan: setback, planned road and public right-of-way before the building permit, based on the zoning plan in force.
 Topographic plan: knowing your land before buildingTopographic plan of a plot under ONIGT Standard 03: survey tied to Lambert and NGM, contour lines, spot heights and files delivered to the architect.
Written by the surveying engineers of DATUM ENGINEERING, a firm registered on the roll of the ONIGT (National Order of Surveying Engineers).
General information article, based on the standards of the ONIGT (National Order of Surveying Engineers) and the ANCFCC (National Agency for Land Registry, Cadastre and Cartography) and on the texts in force on the date of update. It does not replace an examination of your file.